I'm not an insurance agent — I'm the guy your insurance company calls to dry your house out. But after twenty years of water damage jobs across Livingston County, I've watched hundreds of families find out what their policy actually covers, sometimes the hard way. Here's the plain-English version I give my own customers.
The One Rule That Decides Almost Everything
Insurance generally covers water damage that is sudden and accidental. It generally does not cover damage that happened gradually or from neglect. Almost every claim dispute I've seen comes back to that distinction.
Usually Covered (Sudden & Accidental)
- Burst pipes — including frozen pipes that let go during a Michigan cold snap
- Water heater failure — the tank lets go and floods the basement
- Appliance failures — washing machine hoses, dishwasher supply lines, fridge ice makers
- Roof leaks from storm damage — a branch goes through the roof in a windstorm
Usually NOT Covered
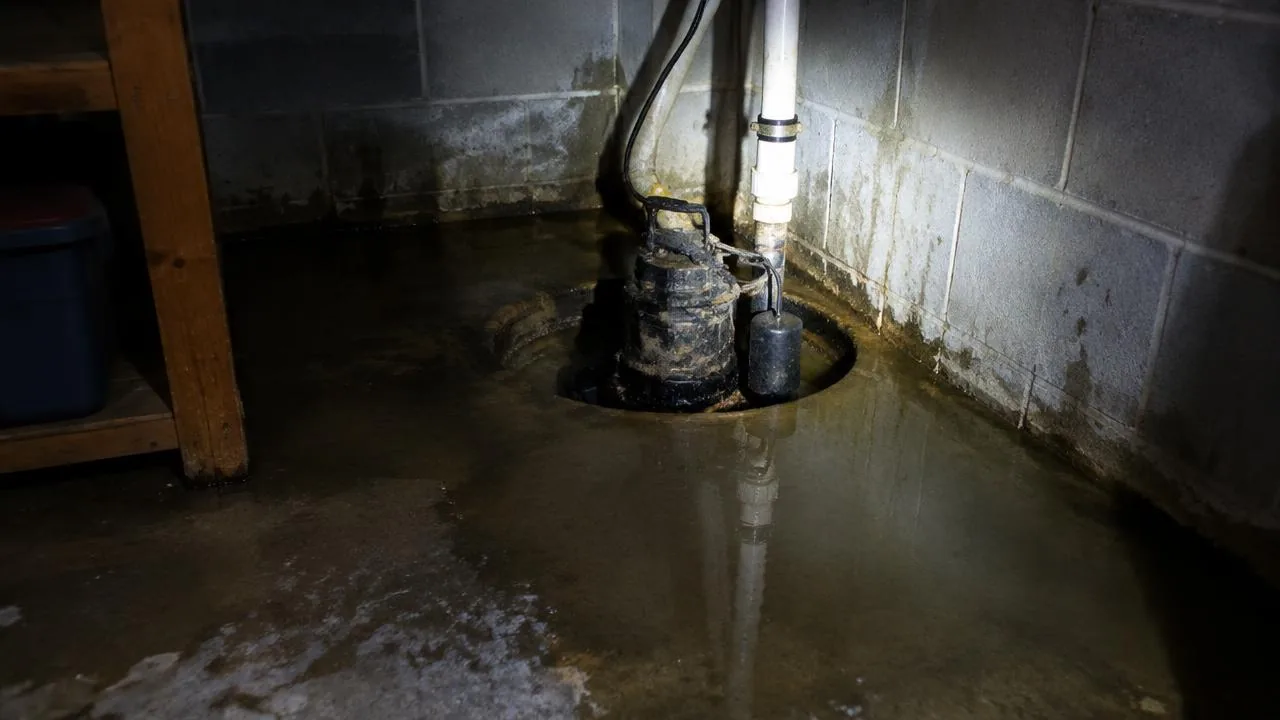
- • Sump pump failure or sewer backup — unless you added the water backup endorsement (more on this below)
- • Groundwater seepage — water coming through foundation walls or the floor after heavy rain
- • Overland flooding — requires separate flood insurance through FEMA's National Flood Insurance Program or a private carrier
- • Slow, long-term leaks — the pipe that's been dripping inside a wall for six months
- • Neglected maintenance — a roof you've known was failing for years
The $50-ish Endorsement Most Michigan Homes Don't Have
Here's the gap that surprises people most: sump pump failure. It's one of the most common ways Michigan basements flood — especially in our clay soil around Howell and Brighton — and a standard policy typically doesn't cover a dollar of it.
The fix is an endorsement called water backup and sump pump overflow coverage. Most agents can add it to a Michigan policy for a modest annual cost. Given that a finished basement restoration can run into five figures, it's some of the best money you can spend. Call your agent this week and ask two questions: do I have it, and what's my limit?
What About Mold?
Mold coverage is usually tied to the cause. If mold grows after a covered sudden event — say, that burst pipe — remediation is often covered up to a policy limit. If it grew because a slow leak went ignored for months, you're probably on your own.
This is exactly why I push so hard on fast, verified drying. Mold can start within 24-48 hours. A water job handled properly in the first two days rarely becomes a mold job. One that "felt dry" after some box fans often does. Our mold prevention guide goes deeper on that timeline.
How to Help Your Claim Go Smoothly
- Document before you clean up. Photos, video, and the water line on the wall. Keep the failed part (hose, pump, fitting) as evidence.
- Act to prevent further damage. Policies actually require this — extraction and drying aren't optional while you wait for an adjuster.
- Get a professional moisture report. When we do a water damage restoration job, we document moisture readings and drying logs in the format adjusters expect. It moves claims along.
- Know your deductible math. For smaller losses near your deductible, get the restoration estimate first — then decide whether filing makes sense for you.
The Bottom Line
Read your policy before you need it, add the water backup endorsement if you don't have it, and if water does get in — move fast and document everything. And if you're standing in water right now, call (517) 300-2445. We answer water emergency calls 24/7, and we'll help you document it right from the start.